Crafting a Letter of Intent for Business Purchase
Small Business Acquisition, Letter of Intent, Buying A Business
How to Write a Letter of Intent (LOI) When Buying a Small Business
A clear, specific Letter of Intent is one of the most powerful tools you have when Buying A Business. Done well, it sets expectations, prevents misunderstandings, and can save thousands in legal fees and weeks of wasted time. Done poorly, it becomes a vague “handshake” that invites surprises, renegotiation, and failed deals. This guide walks you through how to draft a tight, professional Letter of Intent for a Small Business Acquisition, including the 11 essential components every buyer should insist on before engaging attorneys.
Why Your LOI Matters More Than You Think
In many small business deals, both parties rush to “get something signed” so they can start due diligence and “let the lawyers figure out the details later.” That mindset is expensive. A loose, hurried LOI often leads to:
Attorneys spending hours rewriting basic business terms that should have been agreed up front.
Sellers feeling “bait and switched” when the purchase agreement looks different from what they thought they agreed to.
Deals collapsing late in the process, after both sides have invested significant time and money in a flawed Due Diligence LOI.
A well-crafted LOI does not try to replace the purchase agreement. Instead, it captures the core business deal in plain language: what you are buying, how much you are paying, how it will be financed, and under what conditions you will actually close. The tighter your LOI, the more focused and efficient your attorneys can be, and the lower the risk of surprises that blow up trust and kill momentum.
💡 Power of BIZ Principle: Specifics beat speed. Take an extra day to clarify your LOI and you can save weeks in negotiation later.
Common LOI Mistakes First-Time Buyers Make
First-time buyers are often eager and optimistic. That energy is valuable, but it can lead to predictable LOI errors that cost real money. Some of the most common mistakes include:
Overly vague purchase terms. Phrases like “price to be determined after due diligence” or “structure to be finalized later” leave massive gaps that invite conflict once new information emerges.
No clear deal structure. Not stating whether this is an asset purchase or stock purchase, or what is included in the sale, is a recipe for misunderstanding and re-trading the deal.
Skipping financing details. Assuming you will “figure out the loan later” without stating basic financing assumptions in the LOI can leave the seller exposed and you overcommitted to a deal you cannot fund.
No exclusivity or unclear exclusivity. Buyers spend weeks on due diligence only to discover the seller is still shopping the deal to other buyers because exclusivity was never clearly granted or time-bound.
Ignoring non-compete and seller support. Failing to spell out how long the seller will stay involved and what restrictions they will have after closing can undermine the very value you are buying.
Each of these mistakes stems from the same root problem: rushing to sign an LOI before you have really thought through the business deal. A solid LOI Template forces you to confront these issues early, when expectations are still flexible and legal costs are low.
Clarifying LOI terms on paper prevents costly misunderstandings during due diligence and closing.
The 11 Essential Components of a Tight LOI
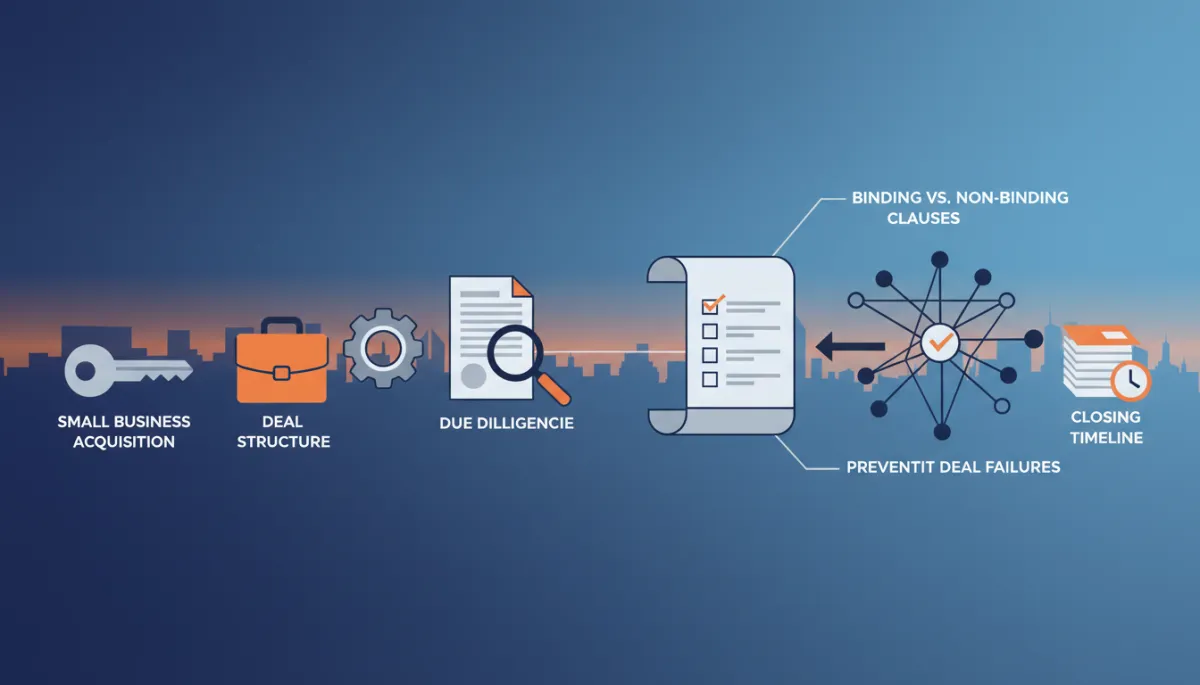
While every Letter of Intent is unique, a strong Small Business Acquisition LOI will almost always address the following 11 components. Think of these as the non-negotiable building blocks of a tight, professional document.
1. Purchase Price: More Than Just a Number
The purchase price is the headline term in any LOI, but it must be defined with precision. At minimum, your LOI should state:
The total consideration you are offering (cash, note, equity, or a mix).
Whether the price is fixed or subject to adjustment (for example, based on working capital or final revenue numbers).
Any earn-out or performance-based component, including how it will be measured and over what time period.
A vague line such as “Price: approximately $1M, subject to due diligence” is an invitation to renegotiate. A stronger approach is: “Buyer will pay a total purchase price of $1,050,000, consisting of $850,000 in cash at closing and a $200,000 seller note, subject to a customary working capital adjustment.”
2. Deal Structure: Asset vs. Stock and What’s Included
The deal structure affects taxes, liability, and what exactly you are buying. Your LOI should clearly state whether this is:
An asset purchase (you acquire specific assets and assume selected liabilities), or
A stock or membership interest purchase (you acquire the entity itself, including all assets and liabilities unless excluded).
Spell out key inclusions and exclusions: inventory, equipment, intellectual property, customer lists, trade names, websites, leases, cash, and accounts receivable. The more clarity you build into the LOI, the easier it will be for your attorney to draft a purchase agreement that mirrors the business deal you intended.
3. Financing: How the Deal Will Actually Be Funded
Financing is one of the most sensitive aspects of Buying A Business. Sellers want confidence that you can close; you want flexibility if bank terms change. A solid LOI strikes that balance by outlining:
The expected source of funds (e.g., SBA loan, conventional bank loan, private lender, personal equity).
Any seller financing, including principal amount, interest rate, term, and security (if known at this stage).
Whether your obligation to close is contingent on obtaining financing on “commercially reasonable terms.”
Including financing assumptions in your Due Diligence LOI sets realistic expectations and protects you if lenders require changes to the deal structure or price later on.
4. Earnest Money: Showing Commitment Without Overexposing Yourself
Earnest money (or a good-faith deposit) demonstrates to the seller that you are serious. Your LOI should address:
The amount of the deposit and when it will be paid (often upon signing a definitive purchase agreement, sometimes at LOI signing into escrow).
Who will hold the funds (typically an attorney or third-party escrow agent).
Under what conditions the deposit becomes non-refundable and any exceptions (e.g., failure to obtain financing, material adverse findings in due diligence).
First-time buyers sometimes agree to non-refundable deposits too early, before they have meaningful access to information. A disciplined LOI ties earnest money risk to specific milestones and findings, not just the passage of time.
5. Due Diligence Period: Scope and Timeline That Work in the Real World
The due diligence period is where you validate everything you think you know about the business. Your LOI should specify:
The length of the initial due diligence period (for small businesses, 30–60 days is common, depending on complexity).
What access you will have: financial statements, tax returns, customer and supplier information, key contracts, employee data, and operational systems.
Any rights to extend due diligence (for example, an additional 15 days by written notice) and whether extensions affect earnest money.
A disciplined Due Diligence LOI makes clear that you are committing time and resources based on the seller’s agreement to provide specific information within a defined window. This keeps both parties aligned and accountable.
6. Closing Timeline: Aligning Expectations From Day One
Your LOI should articulate a realistic closing timeline, usually expressed as a target closing date or a number of days after signing the definitive agreement. Include:
The target closing date (e.g., “on or before October 31, 2026”).
Recognition that the closing date may shift based on financing, third-party consents, or regulatory approvals.
An aggressive date can motivate progress, but it must reflect reality: bank underwriting, landlord approvals, and franchise consents often take longer than new buyers expect. A professional LOI balances urgency with practicality so you do not start the relationship with missed deadlines and frustration.
7. Seller Support: Transition, Training, and Availability After Closing
In small business deals, the owner’s knowledge and relationships are often as valuable as the assets. Your LOI should define what seller support you expect after closing, including:
The length of the transition period (for example, 90 days of part-time support after closing).
The scope of support: training on systems, introductions to key customers and suppliers, support with hiring, or strategic guidance.
Whether the support is included in the purchase price or compensated separately (e.g., a consulting agreement at a defined hourly or monthly rate).
First-time buyers often assume the seller will “stick around as long as needed.” That assumption rarely survives contact with reality. A tight LOI converts vague expectations into specific, enforceable commitments.
8. Non-Compete: Protecting the Business You Just Bought
A non-compete clause is essential in most small business acquisitions. You are often buying the seller’s relationships, reputation, and know-how. Your LOI should outline the expected:
Duration of the non-compete (commonly 3–5 years, subject to local law).
Geographic scope (for example, within a certain radius, state, or region, depending on where the business operates).
Restricted activities (operating, owning, or consulting for a competing business in the same industry).
Laws governing non-competes vary by jurisdiction, and your attorney will refine the language. But your LOI should make it clear that a reasonable non-compete is a core condition of your deal, not an afterthought introduced at the eleventh hour.
9. Exclusivity: Protecting Your Time and Investment in the Process
Exclusivity (sometimes called a “no-shop” clause) prevents the seller from soliciting or negotiating with other buyers while you are investing in due diligence and legal work. A well-drafted LOI will specify:
The length of the exclusivity period (often tied to the due diligence window, with possible extensions if both sides are progressing in good faith).
What is prohibited (soliciting, encouraging, or negotiating alternative offers).
Many first-time buyers skip or soften exclusivity to “keep the seller happy.” In practice, that exposes you to the risk of being used as a stalking horse while the seller shops your offer to others. If you are committing real time and capital, you deserve a clear, time-bound exclusivity commitment in the LOI.
10. Conditions to Close: When You Are Actually Obligated to Buy
Conditions to close spell out what must happen before you are required to complete the acquisition. While the definitive agreement will refine these, your LOI should outline key conditions such as:
Satisfactory completion of due diligence in your sole discretion (or defined materiality standards, if you prefer more structure).
Securing financing on terms consistent with those described in the LOI.
Obtaining required third-party consents (landlord approvals, franchisor consents, key customer or vendor consents, regulatory approvals).
Execution of acceptable non-compete and employment or consulting agreements with the seller and any key employees.
Without clearly stated conditions to close, you risk appearing obligated to buy even if material issues emerge. A thoughtful LOI protects both parties by making the path to closing explicit rather than implied.
11. Binding vs. Non-Binding Clauses: What Actually Has Legal Teeth
Most LOIs are intended to be non-binding with respect to the obligation to close the transaction, but binding as to certain process terms. Your LOI should clearly state which provisions are binding and which are not. Typically:
Non-binding: Purchase price, deal structure, financing, closing timeline, and other business terms (subject to definitive agreement).
Binding: Confidentiality, exclusivity, access for due diligence, expense allocation, governing law, and sometimes non-solicitation of employees or customers during the process.
First-time buyers often sign LOIs that are ambiguous on this point, leading to disputes over whether one party “breached” the LOI by walking away or changing terms. A professional LOI uses explicit language: “Except for Sections X, Y, and Z, which are intended to be binding, this Letter of Intent is non-binding and does not obligate either party to consummate the transaction.”
How a Detailed LOI Saves Legal Costs and Prevents Deal Failure
There is a persistent myth that you should “keep the LOI simple” and let the attorneys handle the complexity. In practice, that approach often backfires in three ways:
Higher legal bills. When basic business terms are missing or unclear, attorneys must spend hours negotiating from scratch, redlining drafts back and forth to reach alignment you could have achieved in a single structured LOI conversation.
Emotional friction. When the purchase agreement surfaces surprises—like a non-compete the seller did not anticipate or a different earn-out structure—trust erodes quickly. Parties begin to wonder what else is “hidden in the fine print.”
Dead deals. The later a major disagreement surfaces, the more sunk cost both sides have. That makes compromise harder and walk-aways more painful. Many of these failures trace back to a vague LOI that never forced hard conversations early.
A detailed LOI has the opposite effect. It forces you, as the buyer, to think through price, structure, financing, seller support, non-compete, exclusivity, and conditions to close before you start paying attorneys. It also gives your legal team a clear roadmap, reducing the time (and cost) required to draft a purchase agreement that reflects the agreed deal.
💡 Practical Tip: Use a robust LOI Template as your checklist. Customize the language, but never skip the core sections that protect your capital and your time.
When to Involve Attorneys in the LOI Process
The goal is not to exclude attorneys from your LOI. It is to engage them at the right time and for the right reasons. A professional, acquisition-focused attorney can add value by:
Reviewing your draft LOI for legal landmines and jurisdiction-specific issues, especially around non-compete and binding vs. non-binding clauses.
Ensuring that exclusivity, confidentiality, and access rights are enforceable and aligned with your strategy.
However, you should not expect your attorney to invent the business deal for you. The business terms—purchase price, deal structure, financing, seller support, conditions to close—are your responsibility as the buyer. The more clarity you bring into the LOI before legal engagement, the more targeted and cost-effective your attorney’s work will be.
Putting It All Together: A Strategic LOI for Small Business Acquisition
A strong Letter of Intent is not a formality; it is a strategic tool. It aligns expectations, protects your downside, and sets the tone for a collaborative path to closing. Before you sign your next LOI for Buying A Business, ask yourself:
Have we clearly defined the purchase price, structure, and financing so there is no ambiguity about “what we are actually doing”?
Does the LOI spell out earnest money, due diligence period, and closing timeline in a way that reflects real-world constraints?
Are seller support, non-compete, and exclusivity described in enough detail that neither side will be surprised when the purchase agreement arrives?
Have we clearly articulated the conditions to close and which provisions are binding vs. non-binding?
If the answer to any of these questions is “no,” you are moving too fast. Slow down, refine your LOI, and get the deal you think you are getting down on paper. That discipline is what separates professional acquirers from hopeful first-time buyers—and it is one of the most reliable ways to protect your capital, your time, and your reputation as you build your portfolio of small businesses.